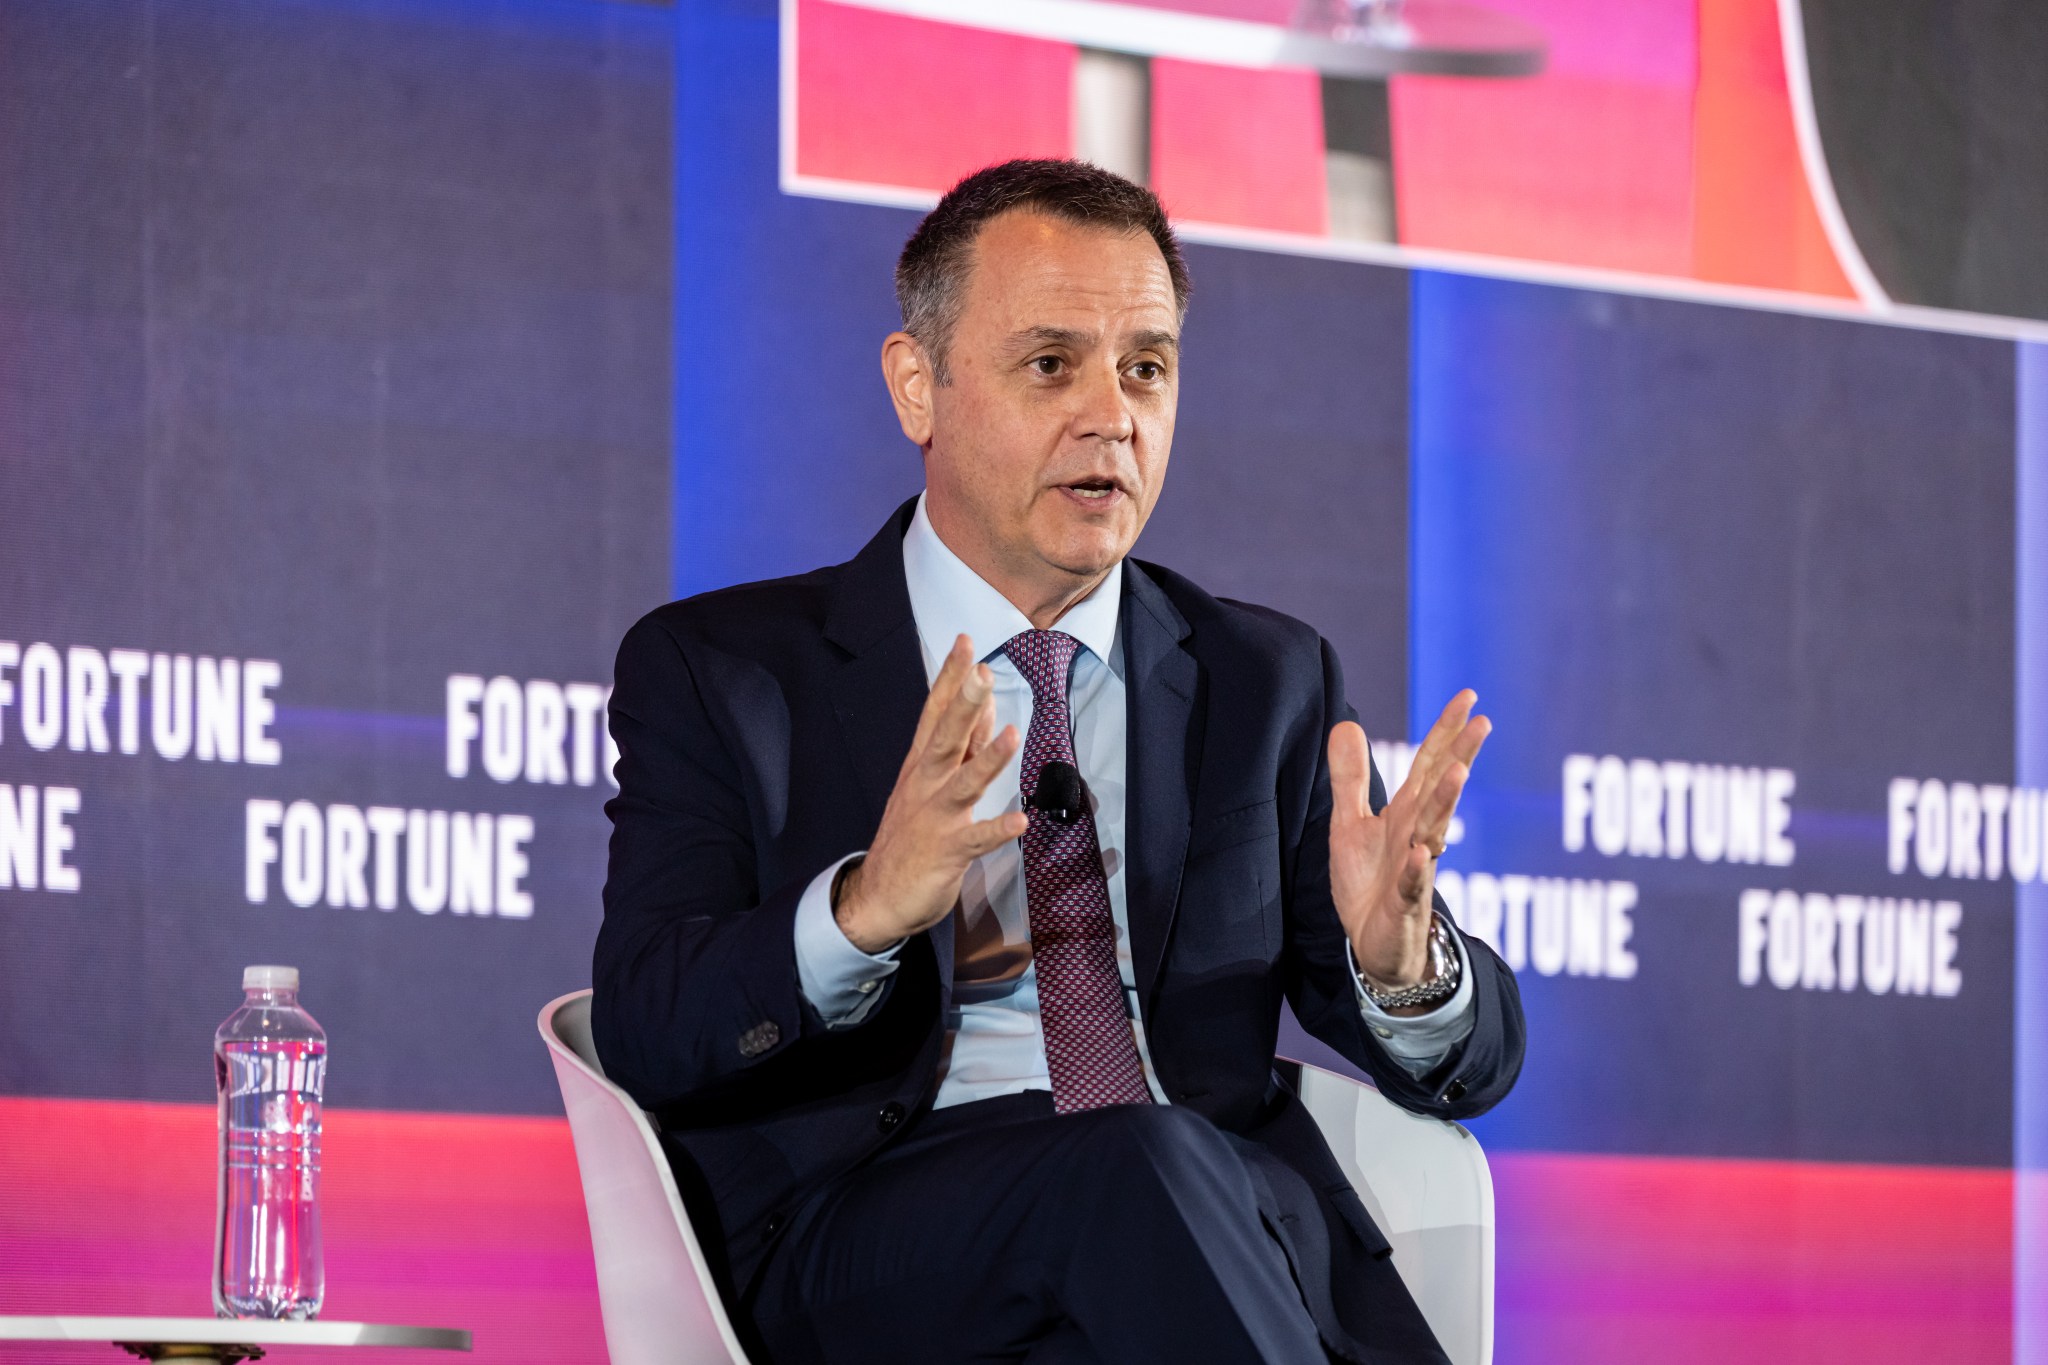
Southeast Asia can still meet the Paris Agreement’s most ambitious climate target, but only if governments across the region accept higher energy costs as the price of decarbonization. That was the central message delivered Tuesday by Guillaume Lucci, president and CEO of Prime Infrastructure Capital, one of the Philippines’ largest infrastructure developers, speaking at Fortune’s Southeast Asia 500 Summit in Ho Chi Minh City, Vietnam. His assessment was frank and, by his own admission, cautious: the 1.5°C goal is technically within reach, but the political will to absorb the costs remains deeply uncertain.
“I do think it’s feasible, but I think it will require sacrificing cost to achieve the objective,” Lucci said onstage. He described himself as “a bit of a pessimist” on whether the region can sustain an AI-era economic growth spurt without blowing past its decarbonization commitments, framing the challenge as a genuine dilemma for governments that must choose between keeping energy affordable for their populations and meeting international climate obligations. The Paris Agreement, signed by countries across the region, commits signatories to holding global average temperature rise to well below 2°C above preindustrial levels, with active efforts to limit warming to 1.5°C. That gap between aspiration and policy is where Southeast Asia currently sits, uncomfortably.
The Philippines illustrates the structural vulnerabilities at stake. The country imports 98% of its oil from the Middle East, a dependence that became acutely dangerous when war broke out in the region in February, triggering a nationwide energy emergency declared in March and sending local fuel prices sharply higher. Lucci connected this geopolitical exposure directly to the grid’s physical limitations. “We have fairly poor grids, certainly not grids that are capable of receiving an abundance of variable energy,” he said, noting that Prime Infrastructure Capital is currently building 2,000 megawatts of pumped hydro capacity in the Philippines specifically to stabilize a grid that is not yet equipped for large-scale renewable integration. The investment is significant, but it underscores how far behind infrastructure development remains relative to climate targets.
The geopolitical dimension of the energy crisis extends well beyond the Philippines. According to the International Energy Agency, roughly 25% of the world’s seaborne oil trade passed through the Strait of Hormuz in 2025, and an estimated 80% of the oil and oil products transiting that chokepoint were destined for Asian markets. Kim-See Lim, chief investment officer of the Asian Infrastructure Investment Bank, noted that LNG prices remain approximately double their pre-conflict levels, and oil prices are close to double as well. The disruption has made the case for energy transition more urgent, not less, even as it raises the short-term cost of doing so.
Lim offered a more optimistic read of the region’s underlying capacity for transformation. Southeast Asia has been the fastest-growing region globally over the past two decades and is projected to continue on that trajectory, she said, and its young, tech-savvy population gives it structural advantages in adopting new energy systems. Crucially, she argued that the main obstacle to clean energy investment is not a shortage of capital but a shortage of confidence. Investors still require minimum returns in emerging markets, and perceived risk remains too high to unlock the financing needed at scale. “Clearly, capital is not lacking,” she said. “What’s lacking really is the confidence, right? And that’s bankable projects.” The implication is pointed: governments and multilateral institutions have a concrete role to play in de-risking projects that private capital will not touch alone, a function that requires exactly the kind of active state intervention that market-first frameworks tend to resist.
Electricity demand across Southeast Asia is projected to rise by 5.4% annually between 2026 and 2030, according to IEA figures, a pace that would strain even a well-functioning grid. Compounding the pressure is the explosive growth of data centers. Global electricity consumption from data centers reached an estimated 415 terawatt hours in 2024, roughly 1.5% of total global electricity use, and the IEA warns that AI is accelerating deployment of high-performance servers, pushing power density higher. Xingjian Pang, Schneider Electric’s East Asia president, noted that the scale of energy and water consumption required by modern data centers is already generating community resistance, forcing facilities to relocate away from population centers toward dedicated energy parks. The infrastructure demands of the digital economy and the infrastructure demands of the energy transition are, in this sense, competing for the same scarce resources, and resolving that tension will require coordinated policy choices that markets alone cannot make.
What emerges from the Ho Chi Minh City summit is a picture of a region at a genuine crossroads. The technical and financial tools for a clean energy transition exist. The investment appetite, in aggregate, is present. What is missing is the political architecture to make the costs acceptable and the returns predictable, a gap that no amount of private-sector optimism can close without governments willing to act as partners, not just bystanders. For a region that will bear some of the heaviest consequences of unchecked warming, the cost of inaction is not abstract.