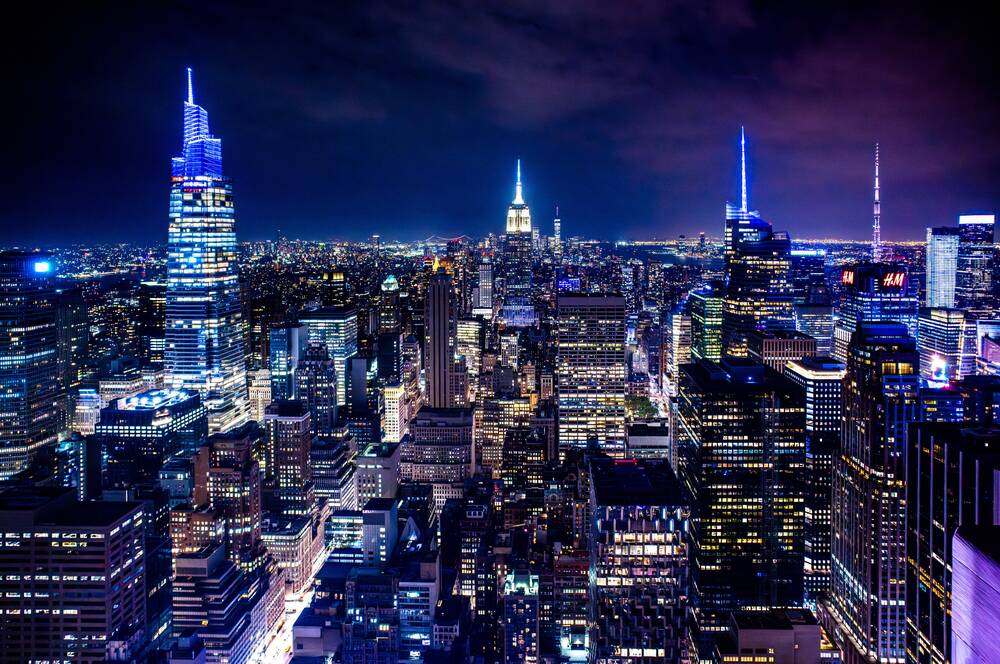
Mortgage rates have climbed back above 7%, and for first-time homebuyers in New York City, that number is not an abstraction. It is the difference between getting a foothold in the housing market and being locked out of it entirely. NYC already ranks as the fifth-hardest metropolitan area in the country for first-time buyers, and a relentless combination of record prices, razor-thin inventory, and now surging borrowing costs is pushing homeownership further out of reach for working and middle-class New Yorkers.
The average rate on a 30-year fixed mortgage eclipsed 7% this week — the fifth consecutive weekly increase — according to Freddie Mac. A year ago, that same rate sat at 6.3%. Rates had briefly dipped below 6% at the start of the year, offering a fleeting window of hope, but fresh economic uncertainty rattled bond markets and sent yields on the 10-year Treasury note above 5%, their highest level in nearly two decades. The bond market moves; buyers absorb the consequences.
What does a 7% rate actually mean for what you can afford?
The math is brutal and worth spelling out plainly. A buyer who could afford a $1 million home at a 5% mortgage rate — putting 20% down on a 30-year fixed loan — can now afford only roughly $807,000 for the same monthly payment at 7%. That is nearly a 20% reduction in purchasing power. Sellers in the New York metro area have not cut prices by 20%. Not even close. Buyers are simply absorbing that gap out of their household budgets, month after month, on top of property taxes, insurance, and utilities that in New York add up faster than almost anywhere else in the country.
Starter homes in New York City already cost $1 million or more, and that threshold is spreading outward. The number of New York towns where entry-level homes carry a seven-figure price tag grew from 31 to 41 in just one year. That is not a housing market functioning in the public interest. It is a market that has been structurally deformed by decades of underbuilding, exclusionary zoning, and policy failures at every level of government — failures that fall hardest on younger, lower-income, and non-white buyers who entered the market latest and with the least accumulated wealth.
Who is being hit hardest — and why?
First-time buyers are bearing the sharpest end of this crisis. The average age of a first-time homebuyer has risen to nearly 40, according to the National Association of Realtors — up from 28 in 1991. That figure alone tells a story about generational wealth erosion. People are not choosing to rent through their thirties; they are being priced out, year after year, while the window of affordable entry keeps closing. Mortgage applications fell 1.5% compared to the prior week, according to the Mortgage Bankers Association, a sign that buyers are already retreating from a market that has become too costly to enter.
Existing home sales have been in a prolonged slump and hit their 2026 low in August, with pending sales running negative compared to last year. Yet even with demand softening, median sales prices on existing homes have risen for 38 consecutive months, reaching $429,100 nationally as of August. The reason is structural: Freddie Mac estimates a national housing shortage of 3.7 million units, a deficit built over decades of underinvestment in public and affordable housing and the quiet triumph of NIMBYism in local zoning battles. Demand softens; prices hold. Supply never catches up.
Are there any lifelines for buyers in New York?
Some relief mechanisms exist, though they are modest relative to the scale of the problem. The NYC Housing Preservation and Development agency offers down payment assistance of up to $100,000 for qualifying first-time buyers — a meaningful sum, but one that barely dents a million-dollar purchase price. The State of New York Mortgage Agency provides mortgage programs with low down payment requirements and below-market interest rates for eligible buyers. On the cost side, buyers can exercise some control over closing expenses: shopping for their own title insurance provider can save between $500 and $1,500, and structuring a purchase to fall below the mansion tax threshold avoids an additional levy that kicks in on sales above $1 million.
Nadia Evangelou, principal economist and director of real estate research at the National Association of Realtors, offered a measured assessment: “Seven percent certainly isn’t what buyers want to see. But I don’t think 7% will stop the market.” That may be true for buyers who already have equity, family wealth, or dual professional incomes. For the first-time buyer in their late thirties, renting in Queens or the Bronx and trying to scrape together a down payment, 7% is not a minor headwind. It is a wall.
What would actually fix this?
Economists do not expect meaningful improvement in the near term. Mortgage rates are likely to remain elevated as long as Treasury yields stay high, and the structural housing shortage that underpins prices will not resolve itself through market forces alone. The evidence accumulated over the past decade is unambiguous: the private market, left to its own devices, will not build enough affordable housing in high-demand cities. That requires public investment, aggressive zoning reform, and a political willingness to override the preferences of existing homeowners who benefit financially from scarcity.
The crisis in New York is not primarily a story about interest rates. Rates are the accelerant. The underlying fire is a housing system that has been allowed — through political choice, not natural law — to treat shelter as a wealth-building asset for those who already own it, rather than as a public good that a functioning society provides to its people. Until that changes, the average age of the first-time homebuyer will keep climbing, and the dream of ownership will keep receding for the New Yorkers who need it most.